5 Mistakes You Might Be Making As A Business Owner
March 12, 2025

Article by Brad Bulow


While business owners are often passionate about their products or services, they can sometimes overlook essential financial elements that can make or break their business. Understanding the most common financial mistakes and taking proactive steps to avoid them can help you stay ahead of potential pitfalls.


Here are five critical financial mistakes to steer clear of:


1. Not Pricing Your Products or Services Appropriately


One of the biggest mistakes business owners make is failing to properly price their products or services. It's easy to underestimate the importance of a solid pricing strategy, but it's crucial for profitability. Your pricing should reflect the cost of goods, overheads, and a reasonable net profit margin.


To get it right, take the time to analyse your direct job costs, operational expenses, and profit goals. Pricing too low can lead to losses, while pricing too high can drive customers away. Ensure your prices cover both direct and indirect costs, and factor in a reasonable profit margin. As part of this process, don’t forget to assess your competitors and adjust your prices as needed, making sure your business remains competitive in the market. Also, as an owner, ensure you are factoring a fair remuneration/wage owing to yourself, into the costing model.


2. Neglecting an Accounts Receivable and Debtor Collection Plan


Many businesses struggle with overdue payments and slow-paying clients, which can cause cash flow disruptions.


Automate your invoicing and communication wherever possible with accounting software like Xero which makes the process of debtor collection more systematic and ultimately successful. However, it's important to maintain a personal touch when communicating with clients, to keep the relationships strong. Set clear payment terms upfront and establish an efficient follow-up system for overdue accounts. Additionally, consider using a debtor management tool or professional service to help recover late payments. With the right systems in place, you’ll keep cash flowing smoothly and reduce the financial strain on your business.


3. Not Having a Budget and/or Failing to Monitor Regularly


A well-structured budget is vital for tracking the financial health of your business. Unfortunately, many business owners neglect to set one or they fail to monitor it regularly. Without a budget, it’s difficult to gauge whether you're on track to meet your goals or if unexpected costs are spiralling out of control.


You should regularly compare your actual income and expenses to your budgeted figures to identify any discrepancies. Are certain costs exploding? Have there been any one-off expenditures that are skewing the results? Do you need to prepare for seasonal fluctuations or downturns?


Having a personal budget as a business owner is just as important. Many businesses fail not because they lack profitability but because the owner spends excessively or pays themselves too much. Keep a close eye on your business and personal budgets to maintain healthy financial practices.


4. Mismanaging Your Tax Obligations


Business owners often forget to set aside enough funds to cover upcoming tax debts, which can create unexpected cash flow issues when activity statement or tax time comes around.


Work closely with your accountant to determine how much you should be setting aside for GST and tax obligations. If you’re selling an asset, be sure to check for any balancing adjustments or tax implications. If your sales have grown significantly, as can happen in busy years, you may need to adjust your provisions accordingly. Additionally, stay informed about tax rules, such as changes to depreciation rules and instant asset write-off allowances. Proper tax planning can minimise your liabilities, helping you avoid any unwanted surprises at the end of the financial year.


5. Neglecting to Invest in Your Team’s Growth and Development


Your staff are one of your greatest assets, and their growth and development should be a priority. Neglecting this aspect of your business can lead to high employee turnover, decreased morale and a loss of productivity which could result in costly hiring and training expenses.


Investing in your employees' growth doesn’t have to be limited to formal education or training programs. Reward good performance with financial incentives, extra time off or other meaningful rewards. At the same time, if you have underperforming staff, it's essential to address the issue and remove any redundant costs. Poor performers can hurt your business indirectly, damaging culture and morale and affecting your bottom line.


.......................................................................................


Final Thoughts


Managing the financial health of your business requires ongoing attention and strategic planning. By avoiding these common financial mistakes, you can position your business for sustainable growth and success.


If you need help fine-tuning your financial strategies or require advice on how to best navigate these challenges, don’t hesitate to get in touch with us. Together, we can build a more secure financial future for your business.


Disclaimer: The information provided on this blog is for general informational purposes only. While we strive to ensure that the content is accurate and up to date, the advice and information provided on this site should not be construed as a substitute for consulting with a qualified accounting or tax professional. The authors and contributors to this blog do not accept any responsibility or liability for any errors or omissions in the content, or for any losses or damages arising from the use of the information provided.

SHARE POST:

RECENT POST:
August 26, 2026
Five conversations worth having in FY2027 A new financial year brings fresh opportunities, new challenges and important decisions for business owners and individuals alike. Rather than telling you what we think is important, we asked each of our Partners to share the one conversation they believe is worth having as we begin FY2027. Adam O’Sullivan | How has your business adapted to Payday Super? This financial year brings several important changes that businesses should plan for now rather than react to later. One of the biggest is the move towards Payday Super. Paying superannuation closer to each payroll cycle will change how many businesses manage their cash flow, so now is the time to review your processes and consider whether you may need additional working capital or funding solutions. I'd also remind business owners that interest charged by the ATO is no longer tax deductible. If you're carrying ATO debt or reviewing your finance arrangements, it's worth taking the opportunity to ensure your lending structure is as tax effective as possible. Planning ahead today can help avoid unnecessary costs tomorrow and give you greater confidence throughout the year. Brad Bulow | Is Your Business Structure Still Right for You? One question I encourage clients to ask at the start of every financial year is whether they're still operating under the right business structure. As your business grows, the entity that suited you when you first started may no longer be the best option. A review could uncover opportunities around tax planning, asset protection or succession planning, but it's important to understand the potential tax and stamp duty implications before making any changes. I'm also seeing business owners under more pressure than ever before. With changes like Payday Super, increasing compliance obligations and the rapid growth of AI and automation, it's becoming almost impossible to do everything yourself. Build the right team around you. Bring in specialist skills where you need them, outsource where it makes sense and keep your focus on the areas where you add the most value. You'll be in a much stronger position to grow while staying compliant in an increasingly complex business environment. Martin Sammut | Stay Informed on the Federal Budget Every Federal Budget introduces changes that have the potential to affect individuals, families and businesses. While some measures take effect immediately, others roll out throughout the financial year, so it's important to stay informed. Whether it's changes to tax legislation, superannuation, business incentives or cost of living measures, understanding how these announcements apply to your circumstances can make a significant difference to the decisions you make. Rather than waiting until the changes impact you, take the opportunity to have a conversation with your adviser. Together we can review what the Budget means for you, identify any opportunities available and ensure you're well prepared for the months ahead. Being proactive, not reactive, is one of the best investments you can make in your financial future. Andrew Manners | Lean on Your Trusted Advisers If there's one thing I'm expecting this financial year, it's change. Whether it's interest rates, Government policy, economic conditions or new legislation, businesses will need to be ready to adapt. During periods of uncertainty, it's more important than ever to lean on your trusted advisers. Your accountant, banker, financial adviser and legal team all play an important role in helping you make informed decisions. When your advisers work together, you're in a much stronger position to build the right processes, strengthen your business structure and identify opportunities as they arise. Don't wait until a challenge presents itself. Schedule the conversations early, review your plans regularly and make sure your business is prepared for whatever the year ahead may bring. A proactive approach will always put you in a stronger position than a reactive one. Danny Riggs | Set Financial Goals That Drive Success The start of a new financial year is the perfect time to set yourself some meaningful financial goals. Whether it's reducing your mortgage below a certain balance, achieving a target turnover, improving profitability or building stronger cash reserves, having a clear target gives you something to work towards. I've always believed that what gets measured gets done. When you create a financial goal, it naturally changes your behaviour. You make better decisions, stay accountable and keep moving in the right direction. Even if you don't quite reach the target, you'll almost certainly be better off than if you hadn't set one at all. My advice is simple: don't let another financial year pass without deciding what success looks like for you. Write your goals down, review them regularly and make them part of your decision-making throughout the year.
June 10, 2026
From 1 July 2026 , new Anti-Money Laundering and Counter-Terrorism Financing (AML/CTF) requirements will apply to accounting firms across Australia. These changes are being introduced by AUSTRAC (the Australian Transaction Reports and Analysis Centre) to help protect Australia's financial system, improve transparency, and reduce the risk of criminal activity. While the legislation is new for accounting firms, the process may already be familiar to many clients. Similar identity and verification checks have long been required by banks and other financial institutions. As a result, we may need to request additional information from some clients, including: Identification documents Updated business or entity information Details about beneficial ownership and control We understand these requests may feel like extra administration. Our goal is to make the process as simple and straightforward as possible while meeting our obligations under the new regulations. Our team is already preparing for these changes through training, process reviews, and system updates to ensure a smooth experience for our clients. Protecting your privacy remains a priority. Any personal information or identification documents provided to us will be handled securely and only through providers that meet strict data protection standards. What does this mean for you? If we ask for additional information from 1 July 2026 onwards, it will likely be because we are required to do so under these new AML/CTF obligations. If you have any questions about the upcoming changes, please don't hesitate to contact our team. Disclaimer: The information provided on this blog is for general informational purposes only. While we strive to ensure that the content is accurate and up to date, the advice and information provided on this site should not be construed as a substitute for consulting with a qualified accounting or tax professional. The authors and contributors to this blog do not accept any responsibility or liability for any errors or omissions in the content, or for any losses or damages arising from the use of the information provided.
June 4, 2026
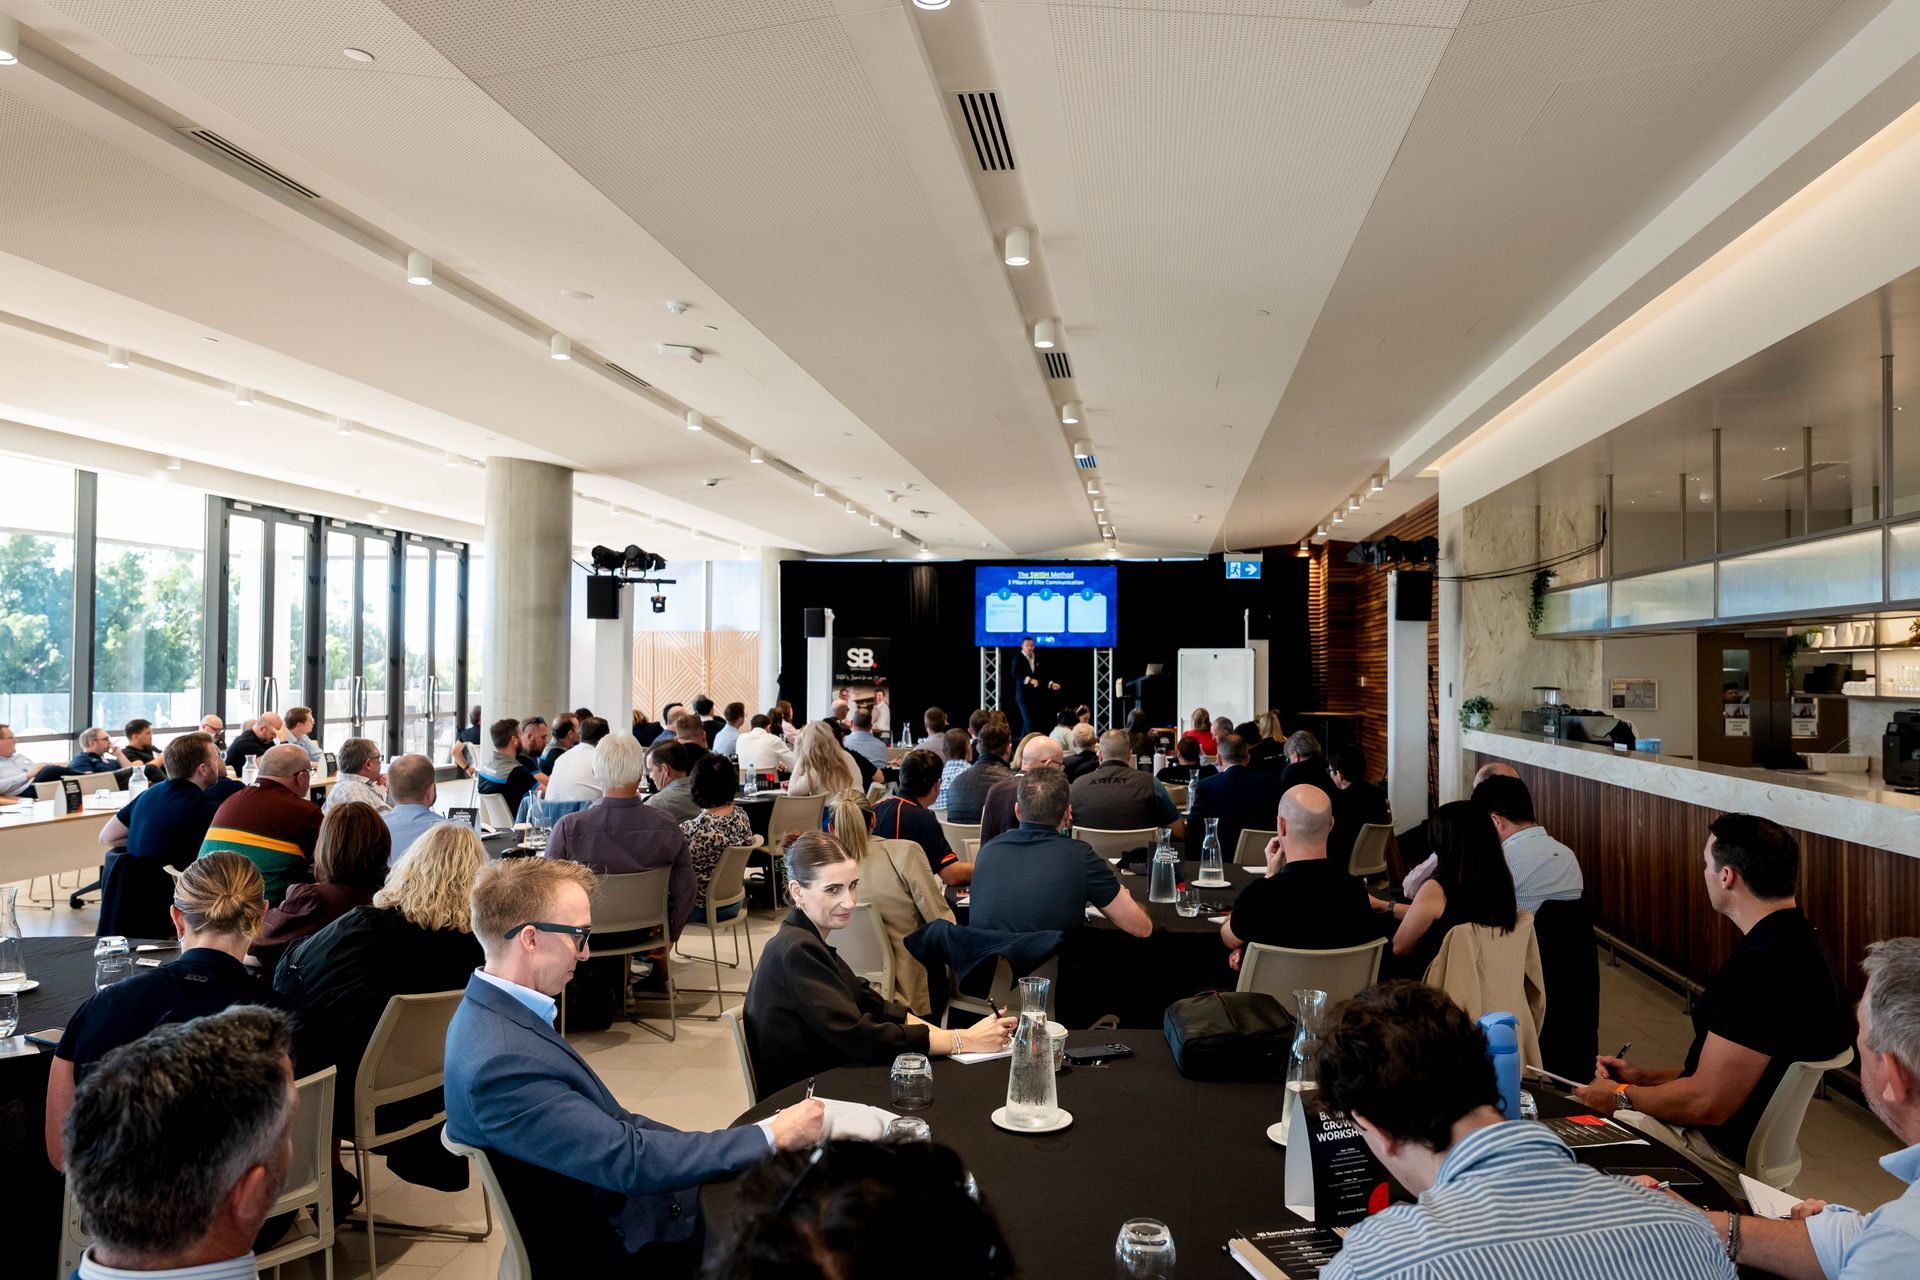
Better Conversations. Better Business. Recently, we had the pleasure of welcoming business owners and leaders from across the Ipswich region to our Business Growth Workshop featuring Ryan Tuckwood. The room was filled with people from a wide range of industries, all investing time away from their businesses to learn and connect with others who share a commitment to growth. While Ryan is widely recognised as one of Australia's leading sales strategists and the founder of SWISH (Selling With Integrity & Selling Honestly), the day quickly became about something much bigger than sales. It became a conversation about people. Because whether you're leading a team, growing a business, managing clients or developing partnerships, the quality of your conversations often determines the quality of your outcomes. One of Ryan's core philosophies is simply "Study people, not sales. When you do, success follows.
April 24, 2026
At Sammut Bulow, we’ve recently seen an increase in clients receiving unofficial registry notices via the post and email relating to ASIC annual company statements and annual review fees. At first glance, these communications can look legitimate. They often use formal language, reference ASIC requirements, and may suggest they are acting on behalf of your business or can assist with lodging your annual review. In some cases, they also request payment directly. However, many of these notices are not issued by ASIC and are not associated with Sammut Bulow. Why this matters Making a payment to the wrong provider doesn’t satisfy your company’s ASIC obligations and can create unnecessary complications. We’ve seen this lead to: Duplicate payments or payments made to these providers but no work being completed Uncertainty around whether the annual review has actually been completed Missed ASIC deadlines Late fees or compliance issues where the genuine fee remains unpaid The client being removed from our registered agent portal and therefore SB being unable to complete important work For busy business owners, these emails can be easy to mistake for a genuine reminder - particularly when they arrive around the same time as your ASIC annual review. What to look out for To protect your business, it’s worth taking a moment to review any correspondence carefully. As a general rule: Only rely on communications sent directly from ASIC or Sammut Bulow If you receive an invoice or request for payment from another provider, don’t act on it straight away Be cautious of wording that suggests the sender is “acting for” your business when you didn’t actually engage them If something feels unfamiliar, unclear, or overly urgent, it’s worth pausing before taking action When in doubt, ask SB If you receive an email, letter or invoice relating to your ASIC annual review and you’re unsure whether it’s genuine, send it through to our team before making any payment. A quick check with us could save you time, money and unnecessary frustration. Our recommendation These notices are designed to look official and they can easily catch people off guard but taking a moment to verify the source before making payment is one of the simplest ways to protect your business. If you’ve received something recently and would like us to review it, please don’t hesitate to get in touch. Disclaimer: The information provided on this blog is for general informational purposes only. While we strive to ensure that the content is accurate and up to date, the advice and information provided on this site should not be construed as a substitute for consulting with a qualified accounting or tax professional. The authors and contributors to this blog do not accept any responsibility or liability for any errors or omissions in the content, or for any losses or damages arising from the use of the information provided.
April 15, 2026
 You may have recently noticed a message from the Australian Tax Office (ATO) about a “Fuel Response” when logging into your ATO portal. We’ve had a number of clients ask what this means and importantly, how it may support their business. The ATO has introduced this initiative to support eligible businesses experiencing increased cost pressures, particularly around fuel, freight, and general operating expenses. While this is not a cash payment or rebate, it is designed to provide greater flexibility and support where it’s needed most. This may include More flexible payment plans for ATO debts Remission of interest and penalties where appropriate A more practical and supportive approach where businesses are genuinely impacted This approach is all about giving businesses breathing room and time, while still keeping things on track. What this means for you If your business has been impacted by rising fuel or operating costs, the ATO may be more flexible in how and when you meet your tax obligations. However, it’s important to understand: Tax obligations still need to be met Lodgements still need to be completed on time Why you’re seeing this message? The ATO is proactively communicating this initiative to individuals and businesses through their online portals to raise awareness of available support options. This does not mean any action is required — it’s simply letting you know support may be available if needed. Our advice to clients If your business is being impacted by rising costs, we’re here to help you navigate your options; Reviewing your current position Communicating with the ATO on your behalf Setting up payment arrangements where appropriate Making sure you stay compliant while managing cash flow The ATO Fuel Response is a support tool - it’s there to assist businesses who need flexibility, but it doesn’t replace the need for strong financial management and ongoing compliance. If you have any questions about the ATO Fuel Response or your ATO obligations contact us today - we are here to help. Disclaimer: The information provided on this blog is for general informational purposes only. While we strive to ensure that the content is accurate and up to date, the advice and information provided on this site should not be construed as a substitute for consulting with a qualified accounting or tax professional. The authors and contributors to this blog do not accept any responsibility or liability for any errors or omissions in the content, or for any losses or damages arising from the use of the information provided.